Interest Rates, Elections, and Stock Cycles: You Make the Call. Stock Talk Update, October 9, 2026

Key Takeaways
- Rate hikes are a headwind, but history says the first hike by itself rarely ends an equity cycle. Earnings and growth usually matter more.
- Earnings remain the strongest support: Q3 S&P 500 EPS growth is estimated near 29.5%, estimates rose during the quarter, and forward valuation has reset near its 10-year average.
- The midterm calendar is turning more favorable: historically, Q4 in midterm years has been strong, especially October and November, although October often includes the quarter’s low.
- The warning: the April 2025 V-bottom is now about 18 months old. Breadth is weak, leadership is narrow, yields are high, and volatility after rate hikes is normal. The bull case is alive, but the margin for error is smaller.
Higher interest rates are back in the headlines. And the easy conclusion is that higher rates must be bad for stocks. But history gives us a much more interesting answer.
Since 1994, the S&P 500 has averaged an 8.7% gain in the 12 months after the first Fed rate hike. Technology has often done even better. So the question for investors is not simply, “Are rates going up?” The better question is: “What is happening to earnings while rates go up?”
Today I want to put four pieces of evidence on the table — rate hikes, earnings, the midterm election cycle, and the age of this bull-market rebound — and then you make the call.
POINT 1 — RATE HIKES RARELY END THE BULL MARKET BY THEMSELVES
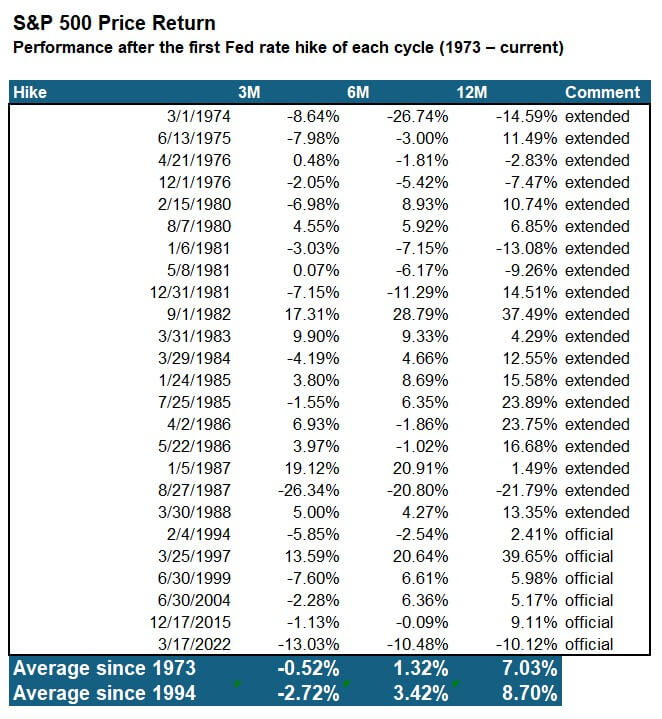
Start with the chart showing S&P 500 returns after the first Fed hike.
The short-term reaction can be messy. Since 1994, the average S&P 500 return three months after the first hike was negative 2.7%. But six months later it averaged positive 3.4%, and after 12 months, positive 8.7%. That is an important distinction. The first hike often creates volatility. It does not automatically create a bear market.
Source: Charlie Bilello, Creative Planning
Look at the individual cycles. After the March 1997 first hike, the S&P 500 gained almost 40% over the next year. After June 1999, it still gained about 6%. Even the longer history back to the 1970s shows many positive 12-month outcomes after the first hike.
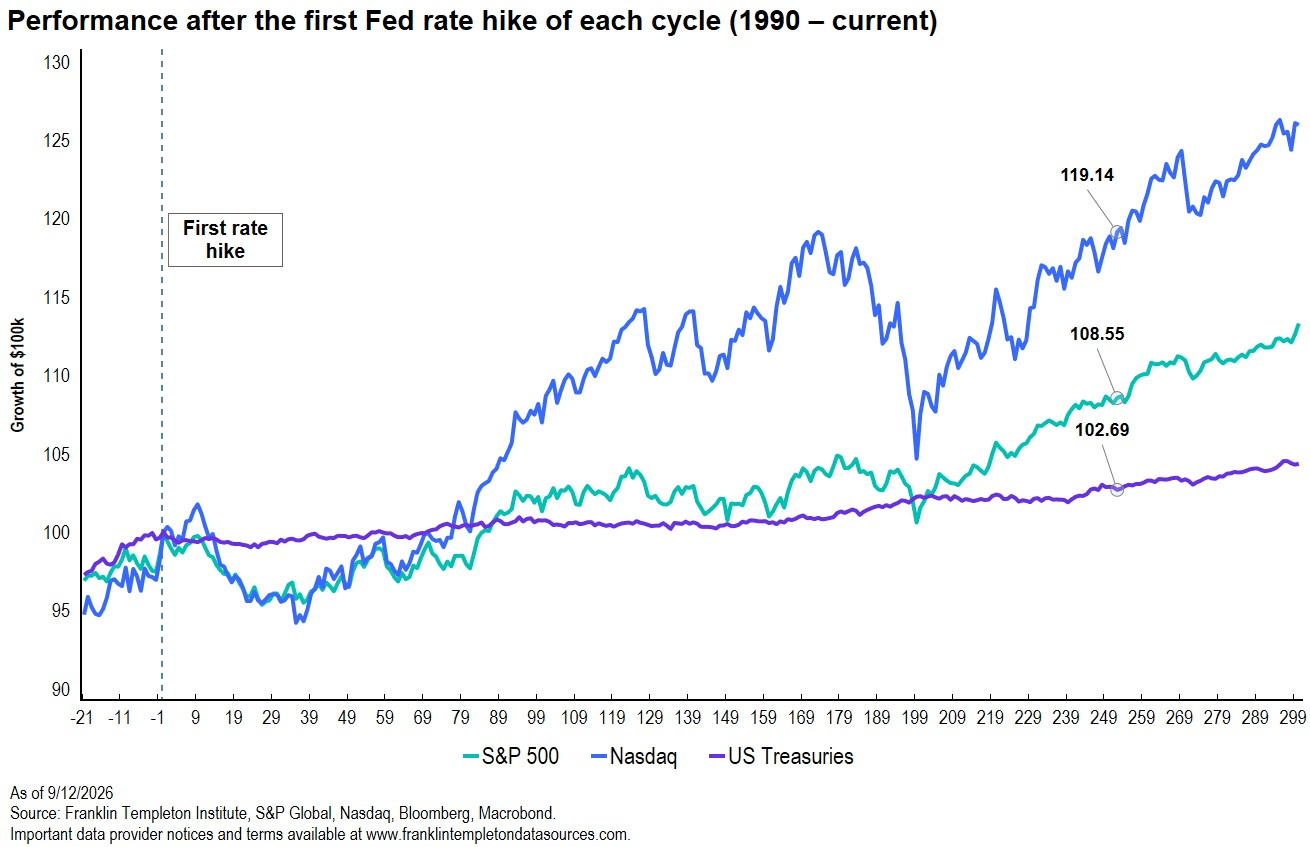
The asset-class chart tells the same story. Over roughly 300 trading days after the first hike, the historical path shows stocks — and especially the Nasdaq — beating Treasuries. And the sector chart is even more surprising: since 1994, Information Technology and Energy have been the two strongest sectors on average in the 12 months after the first hike.
Why? Because the Fed usually raises rates when the economy, demand, or inflation is strong enough to tolerate tighter policy. Higher rates lower the value of future cash flows, but strong earnings and productivity can offset that valuation pressure. That is the same higher-rate paradox we have discussed before: rates matter, but the reason rates are rising matters too.
So point one is simple: a rate hike is a yellow light — not automatically a red light.
POINT 2 — EARNINGS ARE STILL THE BULL MARKET’S BEST DEFENSE
Now we get to what I think matters most: earnings.
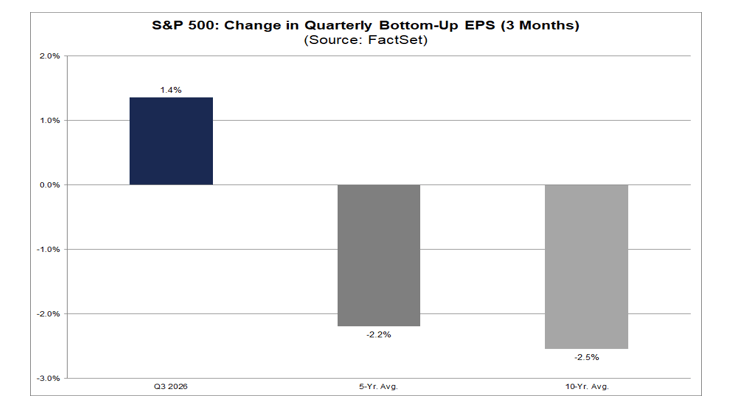
FactSet’s early October numbers show analysts actually raised third-quarter S&P 500 earnings estimates during the quarter. That is unusual. The Q3 estimate rose about 1.4% from the end of June through September, while estimates normally fall by roughly 2% to 3% during a quarter.
The current estimate is about 29.5% year-over-year earnings growth for Q3. If that holds, it would be the third straight quarter with earnings growth above 25%, and the eighth straight quarter of double-digit growth.
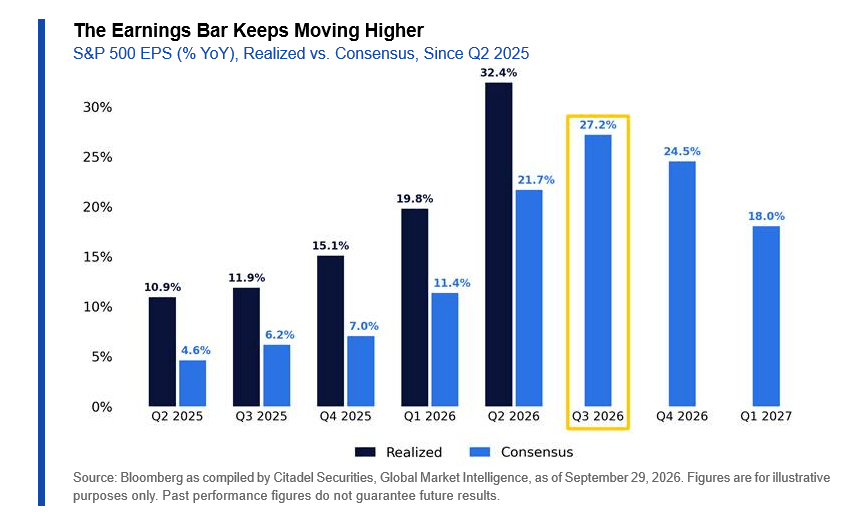
Work from Citadel securities and FactSet tell a similar story. Corporate profits rose 22.8% year over year in Q2 to a record $4.83 trillion. Q3 earnings estimates have continued moving higher, and companies have been clearing a rising earnings bar. And valuations have already adjusted. The S&P 500 is around 19 times forward earnings, close to its 10-year average. Semiconductors have seen a much larger valuation reset. In other words, higher bond yields have already taken some air out of the P/E multiple.
That does not make stocks cheap. But it means the market is no longer relying only on multiple expansion. Earnings now have to do more of the work — and so far, they are. This is the key test for the next few weeks: if earnings estimates keep rising while rates rise, the bull market can survive. If earnings estimates roll over while real yields stay high, the math gets much tougher.
POINT 3 — THE MIDTERM ELECTION CYCLE IS STARTING TO FLIP POSITIVE
The third piece is the calendar.
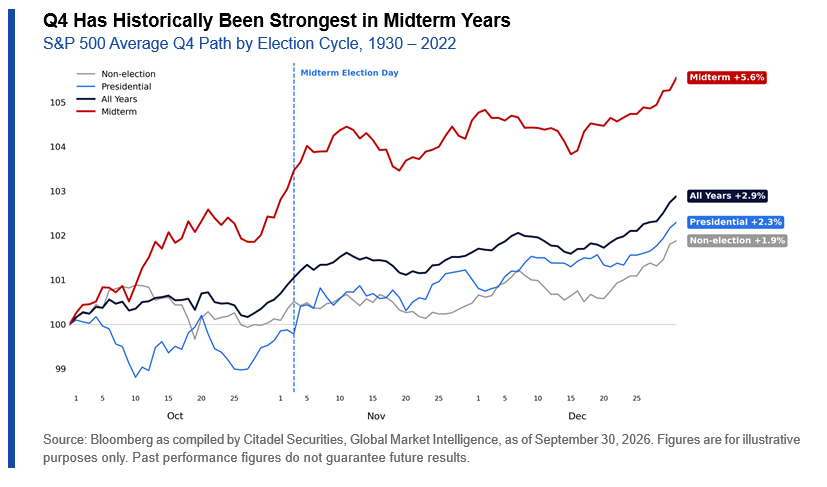
The election-cycle chart shows why the next several months are interesting. Year two — the midterm year — has historically been the difficult part of the four-year presidential cycle. But the weakness has often been front-loaded. As the year moves toward the fourth quarter, the historical pattern improves.
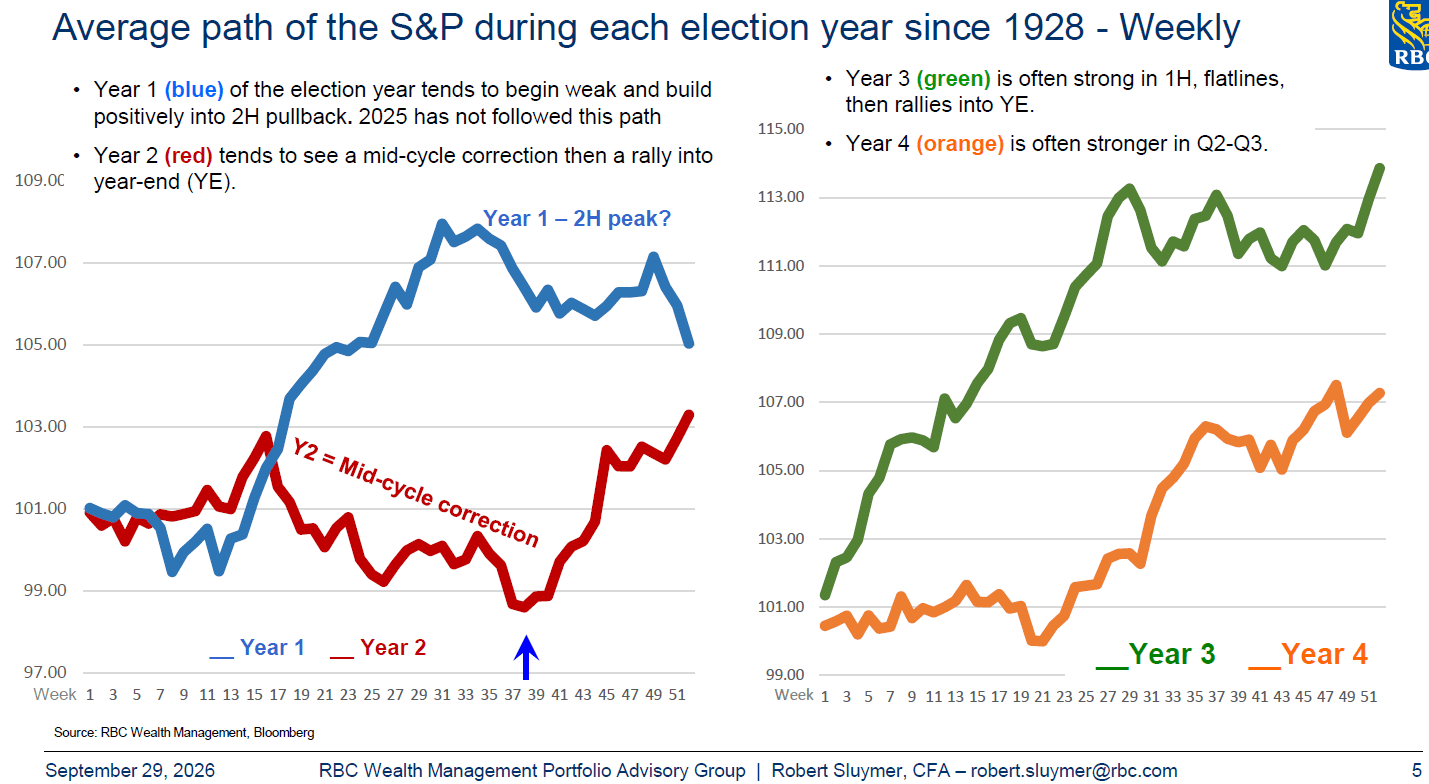
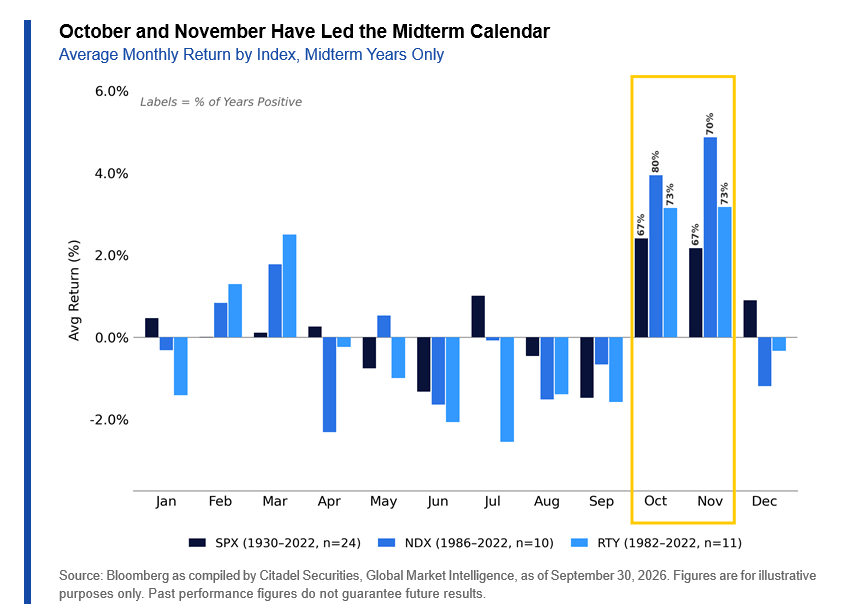
The data going back to 1930 shows the S&P 500 has gained an average 5.6% in the fourth quarter of midterm years, almost twice the 2.9% average for all years. October and November have historically been the strongest months of that midterm calendar. But here is the catch — and it matters for anyone watching the market day to day. The Q4 low occurred in October in 14 of 24 midterm years, or 58% of the sample. From that Q4 low, the median rally into year-end was about 10%. And remember, was DJT’s last midterm election? 4q2018 and back then the SP500 dropped -19.9% into Xmas eve as the Fed and Jerome Powell said they were not yet tight enough.
So, a positive seasonal setup isn’t a guarantee and does not mean a straight line higher. It can mean weakness first, then strength. That fits the rate-hike history too: volatility often rises before the market finds its footing. For retirees, that distinction matters. A normal correction inside a continuing earnings cycle is very different from a fundamental breakdown in earnings, credit, or the economy.
POINT 4 — THE APRIL 2025 V-BOTTOM IS NOW 18 MONTHS OLD
Now for the part that keeps me from getting too comfortable.
The V-bottom from the April 4 through April 8, 2025 tariff shock is now about 18 months old. The market has had a powerful recovery, and recoveries eventually have to prove they can survive without the easy rebound math. The warning signs are not hard to find. Many strategists are noting weak breadth, that the S&P 500 is near its highs, but only about 25% of its members were above their 50-day moving average at the end of September. In Q3, the S&P 500 gained 2%, while equal weight fell 2%, the Russell 2000 fell 7%, and semiconductors fell 11%. The Magnificent Seven gained 11%. Even more striking, Microsoft, Nvidia, Apple and Meta contributed roughly 300 S&P 500 points during Q3 — more than 200% of the index’s entire gain — while the rest of the index collectively detracted about 150 points.
That is not automatically bearish. A cap-weighted index can keep rising with narrow leadership. But it does make the market more fragile if those leaders stumble. And remember the volatility chart. In every first-hike cycle shown since 1994, both the S&P 500 and Nasdaq 100 experienced a meaningful three-month drawdown after the first hike. The average experience is not “Fed hikes, stocks go straight up.” The experience is “Fed hikes, volatility rises, then earnings decide what happens next.”
That is why I would call the current setup constructive — but less forgiving than it was at the April 2025 low.
Conclusion
First, rate increases alone have rarely been enough to kill a bull market. Second, earnings growth is still unusually strong and estimates are rising. Third, the midterm calendar is shifting from a seasonal headwind toward a historical tailwind. Those are three real positives.
But the fourth point is the one I would keep on the dashboard. This rebound is no longer young. Market breadth is weak. Leadership is concentrated. Treasury yields are high. And history says volatility around a new hiking cycle is normal, not unusual.
So my answer is not “rates do not matter.” They absolutely matter. Higher rates lower P/E ratios and raise the return investors can earn in bonds and cash. But a bull market usually ends when the rate pressure damages earnings, liquidity, credit, or economic growth — not simply because the Fed raises rates once.
For retirees and near-retirees, I would watch three things more closely than the daily Fed headlines: earnings revisions, market breadth, and credit conditions. If earnings keep rising and breadth begins to improve, higher rates may remain a headwind instead of a roadblock. If earnings weaken and credit spreads widen while rates stay high, the call changes quickly.
That is the market’s version of “You Make the Call.” The evidence still leans constructive — but at 18 months off the V-bottom, the burden of proof is getting higher.
Chris Perras
CFA®, CLU®, ChFC®
Chief Investment Officer, Financial Advisor
Chris is a seasoned investment professional with over 25 years of experience working with some of the most successful money management firms in the world. Chris has made it a point in his career to adapt as the market landscape changes, seeking to utilize the appropriate investment strategy for a given market environment. His transition from managing billions of dollars at the institutional level to helping individuals and families retire is guided by a desire to see first-hand the impact he is making in the lives of clients at Oak Harvest.
Click to subscribe: