Weekend Update, October 12th, 2026
WEEKLY MARKET BRIEF
Week ended October 9, 2026 | Published October 11, 2026

Source: AP market close
Key Takeaways Last Week
Large caps reached all-time highs, but the week was defensive. The S&P 500 gained +1.2%, the + 0.9% and the Nasdaq +0.6%, while the Russell 2000 fell -0.9%. Utilities, staples and energy led as yields held near 5.24%.
- Records without broad risk appetite. The S&P 500 set a closing high Tuesday, but small caps lagged by about 2.1
- Rates stayed restrictive. The 10-year briefly reached 5.36%, its highest area since 2002, before finishing near 5.24%..
- Services inflation stayed hot. September ISM Services was 54.9, with new orders at 59.8 and prices at 74.0.
- The Fed leaned toward another 2026 hike. Officials expected another increase by year-end; with 83% odds to an October hold.
- Consumer stress worsened. sentiment fell to 46.3 and one-year inflation expectations rose to 4.7%.
U.S. Stock Performance – Index and Sector Moves
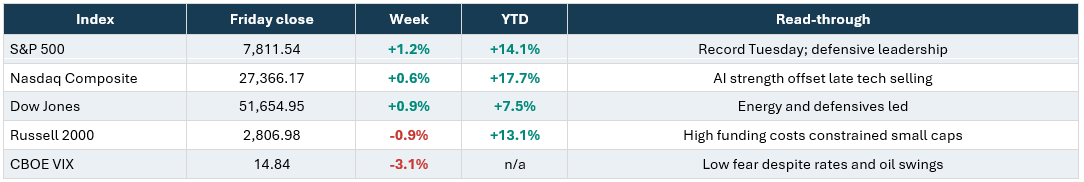
Leadership was defensive. Utilities gained 3.4%, consumer staples 2.4%, energy 2.4% and real estate 2.4%. Communication services fell 1.2%, materials 0.4% and information technology was essentially flat.
Sources: AP market close | tapeboard.com Index and sector data
S&P 500 Stock Leaders and Laggards
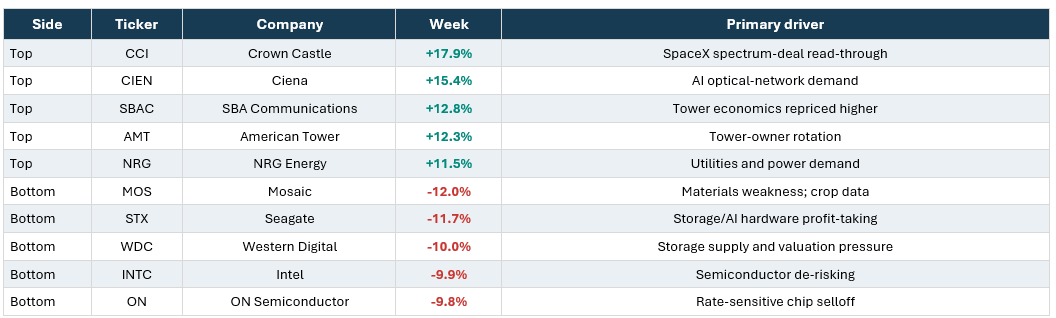
Methodology: Friday-to-Friday price returns, rounded. Drivers identify confirmed news where available and otherwise label the move as market interpretation. Source: AP market close
Mover Detail – Top Five
Crown Castle (CCI), +17.9%: Tower owners surged after SpaceX announced a low-band spectrum purchase that could expand Starlink Mobile;
Ciena (CIEN), +15.4%: The optical-networking rally continued as AI clusters require faster data-center interconnects.
SBA Communications (SBAC), +12.8%: The tower REIT joined the infrastructure rally as the spectrum transaction improved expectations for network leasing demand.
American Tower (AMT), +12.3%: AMT rose with tower peers, benefiting from the same infrastructure-versus-carrier repricing.
NRG Energy (NRG), +11.5%: Power producers benefited from defensive rotation and expectations for higher demand from data centers.
Mover Detail – Bottom Five
Mosaic (MOS), -12.0%: Materials lagged, agriculture plays hit late in week on crop report.
Seagate (STX), -11.7%: Storage hardware reversed as investors sold to extended AI-linked names during the midweek technology selloff.
Western Digital (WDC), -10.0%: The prior week’s supply concerns and profit-taking carried into a broader storage selloff.
Intel (INTC), -9.9%: Semiconductors weakened with renewed scrutiny of AI economics pressured long-duration technology exposure.
ON Semiconductor (ON), -9.8%: Brisking outweighed the week’s advance in the headline S&P 500.
Sources: www.capitalinsightbd.com weekly movers | AP market close
Breadth & Participation
Eight of eleven S&P sectors advanced, an improvement from the prior week. Participation was mixed. Defensive large caps led while small caps fell, technology was flat and communication services declined.
International / Global
Japan and Hong Kong outperformed, with the Nikkei 225 up +1.1% and the Hang Seng up 1+.0%. The FTSE 100 gained 0.9%, while Germany’s DAX fell -0.6%, France’s CAC 40 fell -1.2% and China’s Shanghai Composite declined- 0.7%.
Sources: Global markets
Volatility & Risk Sentiment
The VIX fell 3.1% to 14.84 even as the 10-year Treasury touched 5.36%, oil was volatile and telecom stocks dropped sharply Friday.
Bonds, Credit & Interest Rates
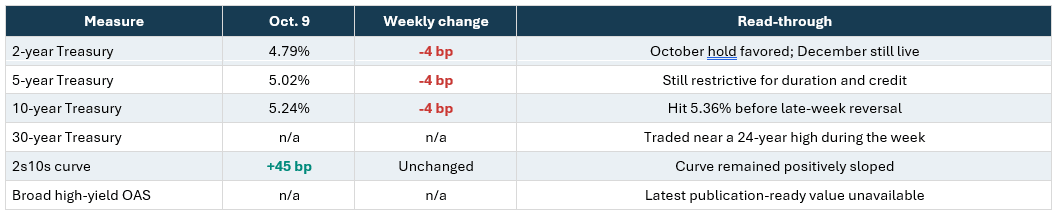
The weekly endpoint looks calm, but the path was not: the 10-year reached 5.36% on Wednesday before strong auction demand and position adjustment pulled yields lower. Rates remain high enough to restrain small caps, housing and leveraged borrowers.
Sources: Federal Reserve H.15 | AP market close
Economic Data, Monetary Policy & Earnings
Services activity stayed firm and inflation pressure remained elevated. September ISM Services eased 0.5 point to 54.9, while business activity was 56.5, new orders 59.8 and prices 74.0. The combination supports growth.
The September FOMC minutes showed most participants thought another rate increase would be appropriate by year-end. By Friday, futures markets assigned about an 83% probability to no change on October 28, shifting the live debate toward December.
Constellation Energy rallied on a Google nuclear-power agreement, Tesla beat third-quarter delivery estimates. Amazon signed a multi-year Synopsys deal worth more than $1 billion. Delta said travel demand remained strong while absorbing materially higher fuel costs.
Sources: ISM Services | FOMC minutes | MarketBeat recap | AP market close
Consumer Stress Commentary
Preliminary October Michigan sentiment fell to 46.3 from 48.1. The survey reported especially steep deterioration among lower-income consumers and households with smaller stock portfolios. This is a direct warning that high food, fuel, housing and borrowing costs are becoming more regressive even while aggregate spending remains resilient.
Sources: Michigan sentiment
Commodities, Currencies & Macro Assets
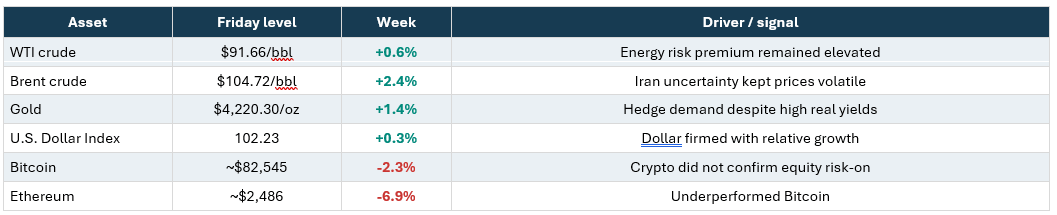
Figures are rounded and may reflect different market cutoffs. The cross-asset message was mixed: stocks and gold rose, the dollar firmed, oil retained a geopolitical premium and crypto weakened.
Sources: tapeboard.com Index and sector data | AP market close
Liquidity Conditions
Liquidity improved during the week ended October 7. Reserve balances rose $81.6 billion to $3.030 trillion as the Treasury General. The reserve increase was supportive, but it did not remove the constraint from high market yields.
Sources: Federal Reserve H.4.1
Flows & Positioning
U.S. equity funds lost $5.11 billion in the week ended October 7, the first outflow in three weeks. Money-market funds absorbed $153.81 billion, their largest inflow since May 6. Global bond funds drew $26.03 billion. The mix favored income over aequity risk.
Sources: marketscreener.com Fund flows
What Matters This Week
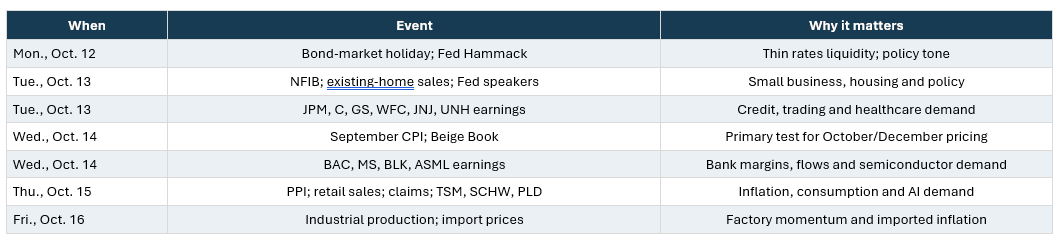
Source: Kiplinger economic calendar
Market Dashboard: The Five Tests
- Inflation: Does Wednesday CPI confirm that energy pressure is spreading, or does core inflation moderate?
- Rates: Can the 10-year hold below 5.30% after reaching 5.36%, or does another global bond selloff restart?
- Breadth: Can financials and small caps participate as earnings begin. Does leadership remain defensive large caps?
- Earnings: Do bank credit quality, net interest margins and capital-markets revenue support the nearly 30% S&P 500 profit-growth expectation?
- Consumer & Oil: Can retail sales and company commentary absorb $100-plus Brent, higher mortgage rates and weak confidence?
Bottom Line
The S&P 500’s 1.2% gain and new record were constructive, but the market did not deliver an all-clear. Defensives led, the Russell 2000 fell, technology was flat, Treasury yields remained above 5% and consumer sentiment weakened. The coming week has a clean decision sequence: September CPI on Wednesday, PPI and retail sales on Thursday, and industrial production on Friday, with major banks and TSMC adding real-time corporate evidence. A constructive outcome would pair moderating core inflation with stable credit and broader earnings participation. The risk case is that energy-sensitive inflation keeps the Fed’s year-end hike path alive while high yields continue to pressure.
Stock Talk
Stock Market Direction 4q2-1q27: The Data-You Make the Call
Selected Sources
MarketBeat recap | AP market close | Federal Reserve H.15 | FOMC minutes | ISM Services
Michigan sentiment | Federal Reserve H.4.1 | Fund flows | Economic calendar
Informational only. Figures are rounded and may reflect different market cutoffs. Metrics marked n/a could not be confirmed at publication. This brief is not personalized financial advice or a recommendation to buy or sell any security.
Past performance is no guarantee of future results. Indexes are unmanaged and one cannot invest directly in an index. They do not reflect any fees, expenses or sales charges. The preceding discussion is for informational purposes only. Investing involves risk and no reference to any security listed above should be considered a buy or sell recommendation. Advisory services are provided through Oak Harvest Investment Services, LLC, a registered investment adviser.