Weekend Update, October 5th, 2026
WEEKLY MARKET BRIEF
Week ended October 2, 2026 | Published October 4, 2026

Source: Seeking Alpha
Key Takeaways Last Week
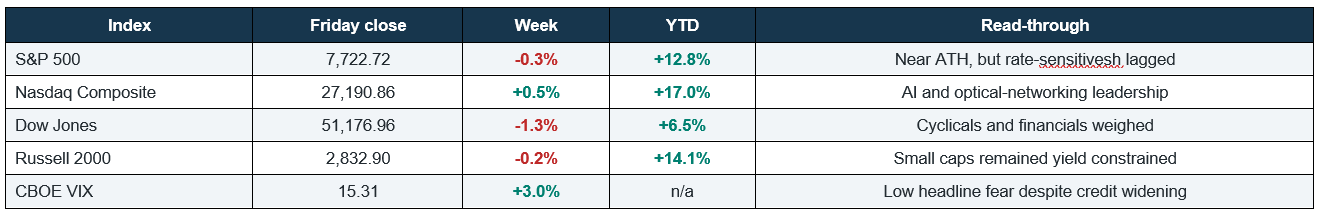
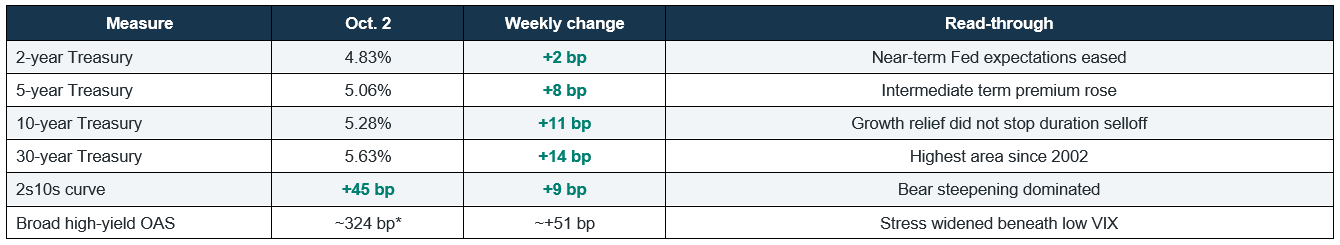
Friday’s weak jobs report changed the rate message. The S&P 500 slipped -0.3% and the Dow fell -1.3%, while the Nasdaq gained 0.5% as AI technology rallied. Ten-year and 30-year yields finished near 5.28% and 5.63%. The probability of an October Fed hike collapsed to 18.3% from 64.2% a week earlier.
- Labor cooled sharply. September payrolls rose 29,000 versus 85,000 expected; unemployment held at 4.2%, and July/August payrolls were revised down by a combined 60,000.
- Inflation slowed. August headline PCE was 3.4% YTY and core PCE 3.0%; September ISM manufacturing prices accelerated to 77.9.
- AI infrastructure broadened. Synopsys, Lumentum and Coherent rallied on stronger photonics and optical-networking demand while technology was the only sector winner on the week.
- Demand signals split. Carnival’s beat and raised guidance lifting cruise stocks. Payments, packaging and disk-drive names weakened as investors punished exposed business models and cyclical uncertainty.
- Calm stock volatility masked tighter internals. The VIX ended at 15.31, yet spreads widened.
U.S. Stock Performance – Index and Sector Moves
Sources: Seeking Alpha weekly movement | AP market close
Sector leadership was narrow. Information Technology gained +1.4%, Energy 1.4% and Utilities 0.7%; Consumer Discretionary slipped 0.2%. Healthcare (-2.7%) and Financials (-2.5%) led the seven declining sectors, followed by Consumer Staples and Real Estate (-1.9% each).
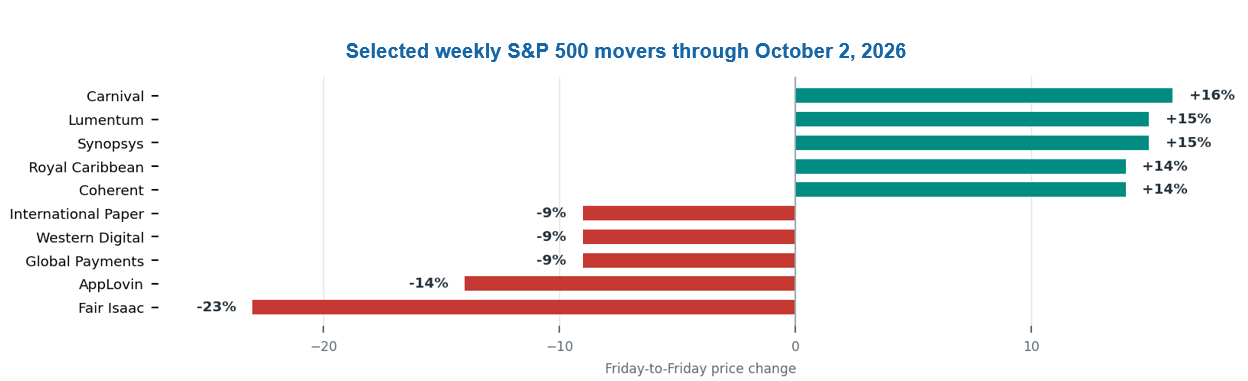
S&P 500 Stock Leaders and Laggards
Source: Seeking Alpha
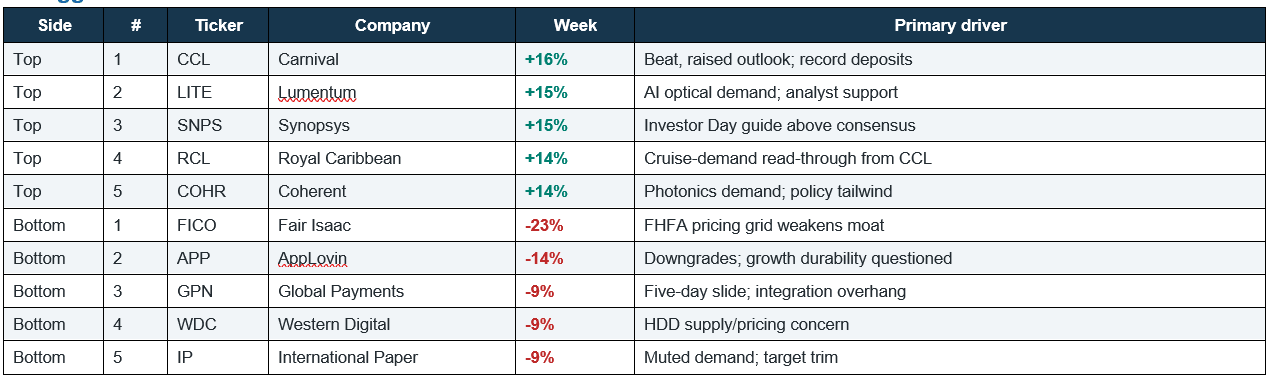
Methodology: Seeking Alpha’s Friday-to-Friday price-return ranking. Corteva’s apparent screen decline was excluded because its October 1 Vylor distribution was a corporate action, not an economic loss. Returns are rounded; company news is separated from interpretation.
Mover Detail – Top Five
Carnival (CCL), +16%: Adjusted EPS of $1.43 beat the $1.35 consensus on record revenue of $8.44 billion. Management lifted full-year adjusted EPS guidance to $2.24, projected EBITDA above $7 billion, and cited record customer deposits of $7.6 billion.
Lumentum (LITE), +15%: The optical-component rally extended as AI clusters require faster links between chips and data centers. Bernstein initiated coverage at Outperform, while reports that Washington may restrict Chinese optical transceivers.
Synopsys (SNPS), +15%: At its September 30 Investor Day, Synopsys guided above the roughly $10.8 billion consensus, outlined a path toward a roughly 50% non-GAAP operating margin by fiscal 2030, and highlighted Amazon and OpenAI partnerships..
Royal Caribbean (RCL), +14%: Rose in sympathy with Carnival’s beat, guidance raise and record forward bookings..
Coherent (COHR), +14%: Coherent joined Lumentum in the AI-interconnect rally. Stronger demand for datacenter photonics, favorable analyst coverage and possible U.S. restrictions on Chinese optical transceivers supported the move.
Mover Detail – Bottom Five
Fair Isaac (FICO), -23%: FHFA’s mortgage pricing framework placed VantageScore alongside FICO, directly challenging the economics of a long-standing franchise. The stock fell more than 26% on Tuesday.
AppLovin (APP), -14%: Wells Fargo moved to Equal Weight and Bank of America to Neutral as analysts questioned the durability of a 30% long-term growth target and the pace of e-commerce traction.
Global Payments (GPN), -9%: Shares declined but no single new company announcement explained the full move. .
Western Digital (WDC), -9%: A Nikkei report that Toshiba plans roughly $380 million of investment to double hard-drive capacity by fiscal 2027 raised supply and pricing concerns for storage vendors.
International Paper (IP), -9%: No discrete company event accounted for the five-day decline. The move also aligned with broad materials weakness rather than a verified earnings surprise.
Sources: Carnival 10-Q | Synopsys catalyst | FHFA credit-score policy | IP weekly history
Breadth & Participation
Participation remained narrow: only four of eleven S&P sectors advanced, and the Nasdaq’s gain contrasted with losses in the Dow and Russell 2000. Technology was the decisive support, while healthcare, financials and defensive staples all fell.
International / Global
Japan was the major exception to a weak global week: the Nikkei rose 2.9%. London fell -2.2%, France -2.2%, Germany -0.7%, China -1.2%, Hong Kong -2.2% and India 2.7%. Higher global yields, renewed dollar strength and persistent inflation pressure weighed on International.
Bonds, Credit & Interest Rates
Sources: Federal Reserve H.15 | Treasury curve | Credit spreads
*Latest available broad high-yield observation was October 1. The 30-year yield traded as high as 5.69% during the week. The key tension is a market pricing less immediate Fed tightening while demanding more compensation for long-duration inflation, fiscal and supply risk.
Economic Data, Monetary Policy & Earnings
Labor softened decisively. September payrolls increased 29,000 versus 85,000 expected, unemployment held at 4.2%, participation was 61.8%, and average hourly earnings rose only 0.1% month over month and 3.0% year over year. https://www.zerohedge.com/markets/jobs-huge-miss-sept-payrolls-plunge-just-29k-below-all-estimates-july-revised-negative
Inflation remained above target but eased. August headline PCE rose 0.3% month over month and 3.4% year over year; core PCE rose 0.2% and 3.0%. Real consumer spending still increased 0.6%, while the saving rate slipped to 4.1%. September ISM manufacturing held at 54.5, but its prices index jumped to 77.9.
October hike odds fell to 18.3% from 64.2% a week earlier, but the long end refused to rally, Accenture beat on revenue and adjusted EPS, and Micron’s strong report did not produce broad semiconductor follow-through.
Sources: BLS employment | BLS JOLTS | BEA PCE | ISM manufacturing
Consumer Stress Commentary
Consumer behavior and consumer mood are diverging. Real spending rose 0.6% in August, but September Michigan sentiment was 48.1, near a multidecade low, as energy, housing and borrowing costs stayed elevated. The weak payroll print and slower wage growth raise the risk that resilient spending becomes harder to sustain, especially for lower- and middle-income households.
Commodities, Currencies & Macro Assets
Sources: Seeking Alpha weekly movement | WTI close
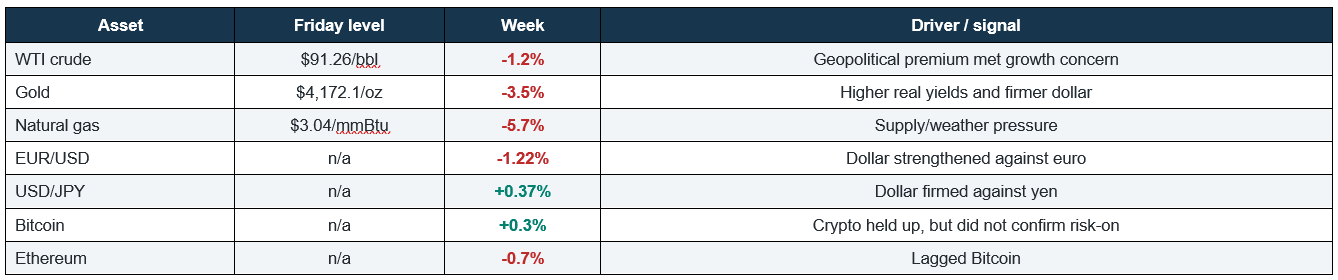
Figures use rounded Friday observations and may reflect different market cutoffs. The macro signal was a stronger dollar and weaker gold despite softer U.S. jobs, because long real yields remained elevated.
Liquidity Conditions
Quarter-end liquidity was orderly but not abundant. September 30, reserve balances rose $17.9 billion to $2.948 trillion and the Treasury General Account -$28.4 billion to $948.7 billion. Reverse repos +$13.1 billion to $329.3 billion, offsetting the reserve benefit…
Sources: Federal Reserve H.4.1
Flows & Positioning
U.S. equity funds drew $20.6 billion in the week ended September 30, the second consecutive inflow, while global equity funds took in $34.8 billion. Technology funds lost $2.6 billion after three weeks of inflows, sector funds lost $0.9 billion and high-yield bond funds lost $2.3 billion.
Sources: U.S. fund flows | Global fund flows
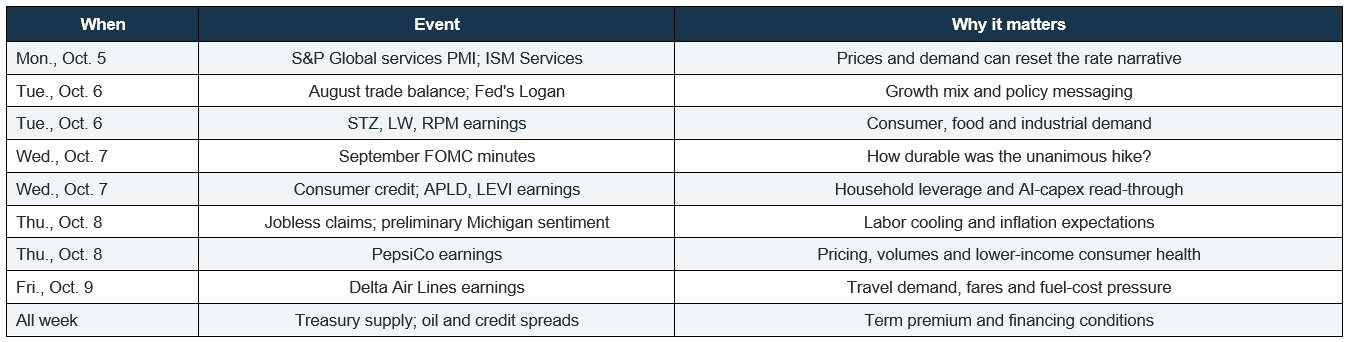
What Matters This Week
Sources: Economic calendar | Earnings calendar | Treasury auctions
Source: Seeking Alpha
Market Dashboard: The Five Tests
- Rates: Can the 10-year hold below 5.30% and the 30-year stabilize after reaching the highest area since 2002? Services prices and Treasury supply are the immediate tests.
- Federal Reserve: Do the September minutes validate a pause on October 28, or emphasize inflation risks enough to keep December tightening live?
- Breadth: Can strength broaden beyond technology, energy and utilities? Watch equal weight, financials and small caps rather than the Nasdaq alone.
- Credit & Liquidity: Does high-yield OAS retreat from roughly 324 bp as reserves rise, or does credit keep tightening while the VIX stays subdued?
- Consumer & Oil: Can spending absorb $90-plus crude, high mortgage rates and slower hiring? ISM Services, sentiment and PepsiCo/Delta commentary are the cleanest near-term reads.
Bottom Line
Friday’s payroll report reduced the risk of an immediate Fed hike, but it did not reverse the week’s tightening in long rates or credit. The Nasdaq was the only major U.S. index higher, supported by AI-linked design and optical-networking names, while seven sectors fell. The constructive case requires stable long yields, narrower credit spreads and better participation; the risk case is that services inflation, oil or Treasury supply pushes term premium higher before labor weakness improves inflation enough.
For the week ahead, the cleanest sequence is: Monday’s services inflation signal, Wednesday’s FOMC minutes, Thursday’s claims and sentiment, then Friday’s travel-demand read-through from Delta. Company dispersion should remain high even if the headline index stays near its record.
Stock Talk
Are Higher Interest Rates Bad for your Retirement Plan?
Selected Sources
Seeking Alpha weekly movement | AP Friday market report | Federal Reserve H.15
BLS employment | BEA PCE | ISM manufacturing
Federal Reserve H.4.1 | Kiplinger calendar | FHFA credit scores
Informational only. Figures are rounded and may reflect different market cutoffs. Metrics marked n/a could not be confirmed at publication. This brief is not personalized financial advice or a recommendation to buy or sell any security.
Past performance is no guarantee of future results. Indexes are unmanaged and one cannot invest directly in an index. They do not reflect any fees, expenses or sales charges. The preceding discussion is for informational purposes only. Investing involves risk and no reference to any security listed above should be considered a buy or sell recommendation. Advisory services are provided through Oak Harvest Investment Services, LLC, a registered investment adviser.