Preparing for Retirement at Chevron: Navigating Your Pension, ESIP, and Tax Strategy

By
Reviewed by Nathan Kattner
For long-tenured professionals at Chevron, reaching age 55 marks a pivotal shift. Decades of contributions across upstream, downstream, or corporate operations have likely built a substantial nest egg. However, transitioning from accumulating wealth to generating predictable, tax-efficient retirement income requires navigating one of the energy sector’s most nuanced compensation structures.
Between the Chevron Retirement Plan (pension), the Employee Savings Investment Plan (ESIP), and company stock holdings, retirement readiness isn’t merely about having a target balance—it is about sequence, tax mitigation, and benefit coordination.
Here are the critical decision points to evaluate 1 to 5 years out from your planned Chevron retirement date.
1. The Chevron Retirement Plan: Evaluating Lump Sum vs. Lifetime Annuity
One of the largest financial decisions you will face is electing how to take your defined benefit pension. Chevron generally offers two core distribution paths: a single lump-sum distribution or a monthly lifetime annuity (with single-life or joint-and-survivor variations).
The Interest Rate Factor
The single lump sum is calculated using IRS segment rates (often referred to in corporate plans as GATT or PPA rates).
- Inverse Relationship: When interest rates are low, the present value required to fund a future income stream increases, leading to higher lump sums. When interest rates rise, lump-sum calculations decline.
- Timing Consideration: A difference in retirement date by just one calendar quarter can shift your lump-sum valuation significantly depending on the rate-lookback month your benefit calculation uses.
Trade-Offs to Weigh
| Feature | Single Lump Sum | Monthly Annuity |
| Longevity Risk | You manage longevity through portfolio withdrawals | Guaranteed regular income for life (or joint lives) |
| Inflation Protection | Potential growth through equity allocation | Fixed purchasing power that erodes with inflation |
| Legacy & Estate | Remaining funds pass directly to your heirs | Typically ends upon the death of you/your survivor |
| Control | Full control over investment allocation and timing | Tied to the financial health and claims-paying ability of the plan |
If you have other guaranteed income sources or wish to maximize wealth transfer to children or grandchildren, a lump sum rolled directly into an Individual Retirement Account (IRA) preserves flexibility. If predictable baseline cash flow covers your lifestyle needs and longevity runs long in your family, the annuity merits careful modeling.
2. Optimizing the Chevron ESIP (401(k))
The Chevron Employee Savings Investment Plan (ESIP) is more than a standard corporate 401(k). For senior professionals, two distinct provisions deserve attention:
Mega Backdoor Roth Strategy
Chevron’s plan structure historically allows for after-tax contributions beyond the standard annual employee deferral limit. When paired with in-plan Roth rollovers or direct rollovers to a Roth IRA, this could create a streamlined vehicle to accumulate hundreds of thousands of dollars in tax-free growth before stepping away from active service.
Managing Company Stock Overconcentration
A common scenario among long-tenured Chevron employees is an ESIP heavily weighted in Chevron Corporation stock (CVX). While company performance may have supported your accumulation years, entering distribution mode with 30%, 40%, or 50%+ of your liquid net worth tied to energy commodity cycles introduces unnecessary sequence-of-returns risk.
Gradually diversifying within tax-sheltered accounts allows you to realign your overall asset allocation with a balanced retirement risk profile.
Mid-Career to Retirement Checklist
Are your savings positioned to withstand inflation, market drawdowns, and upcoming tax rate changes?
Discover where your strategy stands by taking our interactive Retirement Readiness Quiz to evaluate your income plan, tax efficiency, and portfolio risk.
3. The Power of Net Unrealized Appreciation (NUA) for Chevron Stock
If your ESIP contains shares of Chevron stock that have appreciated substantially over years or decades, rolling your entire 401(k) directly into a Traditional IRA could result in paying unnecessary taxes.
Normally, distributions from a Traditional IRA are taxed at ordinary income tax rates (which can exceed 37% at the federal level). Through the Net Unrealized Appreciation (NUA) strategy, you may achieve significant tax savings:
- How It Works: In a qualifying lump-sum distribution, the cost basis of the company stock is distributed and taxed at ordinary income rates in the year of transfer.
- The NUA Portion: The appreciation above the cost basis moves into a taxable brokerage account. This growth is taxed at long-term capital gains rates (currently capped at 20% federal plus the 3.8% Net Investment Income Tax, if applicable) only when the shares are eventually sold.
- The Remainder: The non-stock assets in your ESIP roll tax-deferred into a Traditional IRA.
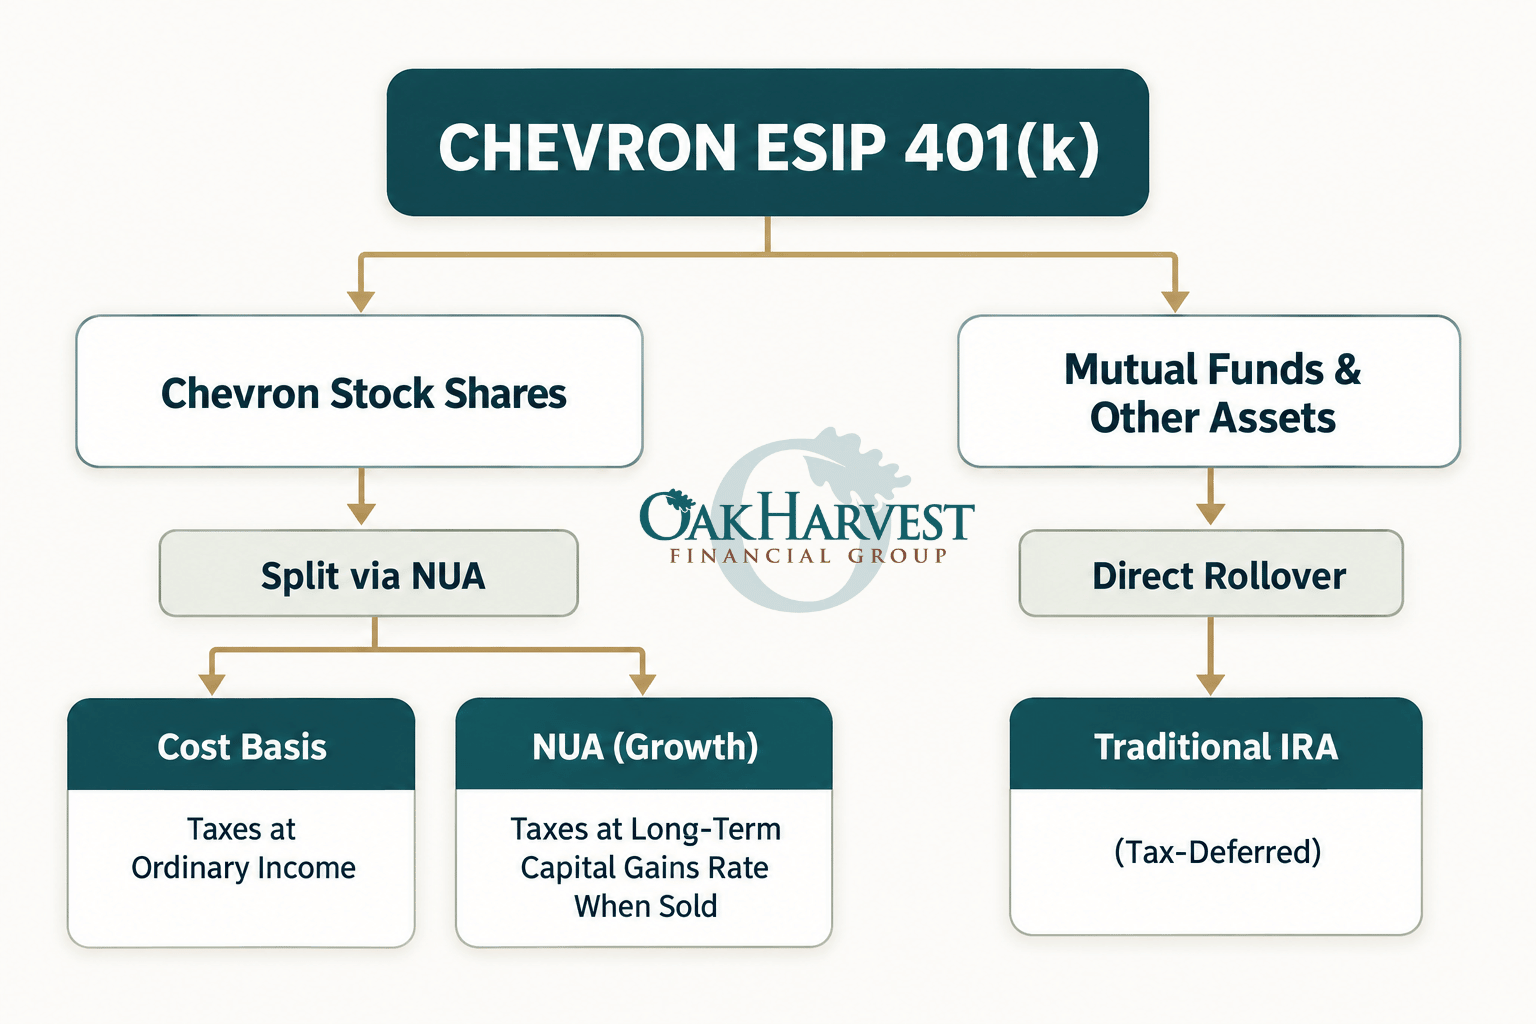
When NUA Makes Sense: It is most powerful when your cost basis is very low relative to current market value. Careful share-lot identification is essential, as only the lowest-basis shares need to undergo NUA while higher-basis shares can be rolled to an IRA.
4. Bridging the Healthcare Gap Before Age 65
Retiring before Medicare eligibility at age 65 requires a concrete plan for medical coverage.
- Retiree Health Coverage: Review Chevron’s retiree medical eligibility formulas (often tied to age and points of service). Understand whether you qualify for Chevron pre-65 retiree health options or a Health Reimbursement Arrangement (HRA).
- Health Savings Account (HSA) Reserves: If enrolled in a high-deductible plan during your working years, your accumulated HSA funds can be deployed tax-free for qualified medical expenses, bridging the gap to Medicare without inflating your taxable income.
5. Tax Coordination: The 55–70 Planning Window
Between your retirement date and the age when Required Minimum Distributions (RMDs) and Social Security begin (ages 70 to 73/75 depending on your birth year), you often experience an intentional “low-income window.”
During this multi-year bracket, disciplined financial planning can significantly alter your lifetime tax burden:
- Roth Conversions: Systematically convert assets from Traditional IRAs to Roth IRAs at lower tax brackets (e.g., filling the 22% or 24% bracket) before pensions, RMDs, and Social Security push your taxable base higher.
- Social Security Claiming Timing: Deferring benefits up to age 70 guarantees an approximate 8% annual delayed retirement credit, providing an inflation-adjusted floor for later years.
Bringing the Pieces Together
Navigating a Chevron retirement involves interconnected decisions where no single choice should be made in isolation. Deciding between a pension lump sum or an annuity directly influences your taxable footprint, which dictates whether an NUA distribution makes sense, which then determines how much room remains for low-bracket Roth conversions.
Because these corporate benefit elections are generally irrevocable, stress-testing your options prior to your final day at Chevron is critical.
Schedule a Complimentary Retirement Consultation
If you are within 1 to 5 years of stepping away from Chevron, our team can help model your options side-by-side. During a complimentary, no-obligation strategy session, we will review:
- Your Chevron Pension Options: A personalized lump sum vs. monthly annuity comparison based on prevailing interest rate trends.
- ESIP & NUA Analysis: A tax-lot breakdown to determine if distributing Chevron stock via NUA offers meaningful tax savings over an IRA rollover.
- Custom Distribution Roadmap: A multi-year income and tax projection designed to preserve capital, manage healthcare bridges, and coordinate Social Security.
To request your conversation, visit oakharvestfg.com or explore our comprehensive guides in our Free Reports tab to start evaluating your timeline today.
Related Oak Harvest Articles:
The Strategic Roth Conversion Ladder: A Planning Tool for More Tax Flexibility in Retirement0
How Long Will My Money Last in Retirement?
What Healthcare Actually Costs as You Age, and the Smarter Way to Plan for It
How to Calculate My Social Security Benefit: A Guide for Your Retirement Strategy
Which States Don’t Tax Retirement Income? What You Need to Know Before You Pack the U-Haul
Let Us Help You Achieve the Retirement You Deserve!
Investment Advisory services are provided through Oak Harvest Investment Services, LLC a Registered Investment Advisor. Insurance services are provided through Oak Harvest Insurance Services, LLC. Oak Harvest Investment Services, LLC and Oak Harvest Insurance Services, LLC are not affiliated with the U.S. government or any government agency. Information presented is for educational purposes only intended for a broad audience. Not an offer or solicitation for the sale or purchase of any specific securities, investments, or investment strategies.
“Peace of Mind,” “Safety,” “Principal Protection,” “Lifetime Income, “Guaranteed Income,” or other guarantees are associated with fixed insurance products. No such language refers in any way to investment advice, investment advisory products, securities, or recommendations provided by Oak Harvest Investment Services. Investing involves risk. Rates of return are not guaranteed unless otherwise stated. All guarantees are dependent on the financial strength and claims-paying ability of the issuing insurance company. Annuities have limitations and are not appropriate for all circumstances or individuals. They are not intended to replace emergency funds or to fund short-term savings or income goals. Lifetime income may be available on certain products through an optional rider, at no cost or for an additional cost, depending on the contract. Insurance products are not insured by any federal government agency and may lose value. By contacting us, you may be offered information regarding the purchase of insurance and investment products.
Oak Harvest has a reasonable belief that this marketing does not include any false or material misleading statements or omissions of facts regarding services, investment, or client experience. Oak Harvest has a reasonable belief that the content as a whole will not cause an untrue or misleading implication regarding the adviser’s services, investments, or client experiences. Please refer to www.oakharvestfg.com for additional important disclosures.